On this page
- Is the HS code for banana chips 0813 or 2008?
- What does Note 1(a) to Chapter 20 actually say?
- Which authority has already ruled on banana chips?
- Why is dried banana probably not heading 0813 at all?
- Why does the code on a supplier’s spec sheet disagree with the customs schedule?
- What does the wrong heading actually cost you?
- Why can’t you find reliable trade data for dried banana?
- What should you ask before you accept a code on an offer?
- What is still open, and what would settle it?
- Common questions
- Related insights
The banana chips HS code depends on two facts about the process, not on the fruit: whether the slice was fried, and whether it was soaked in sugar before drying. Vacuum-fried chips are fried, and frying is not a Chapter 8 process, so they fall in Chapter 20: two UK Advance Tariff Rulings, 600008608 and 600007998, both put fried banana slices in 2008 99 49 80. Soft-dried banana with nothing added stays in Chapter 8, under heading 0803 (EU line 0803 90 90), not 0813. Banana soaked in sugar syrup and then dried moves to heading 20.08.
Is the HS code for banana chips 0813 or 2008?
For vacuum-fried chips, 2008. For plain soft-dried banana, neither: banana keeps its own heading in the dried state, 0803, and the residual dried-fruit heading 0813 does not apply to it. For soft-dried banana that was soaked in sugar syrup before drying, 2008 again. The phrase “dried banana from Vietnam” covers two goods made on two different machines, and an offer document almost never says which.
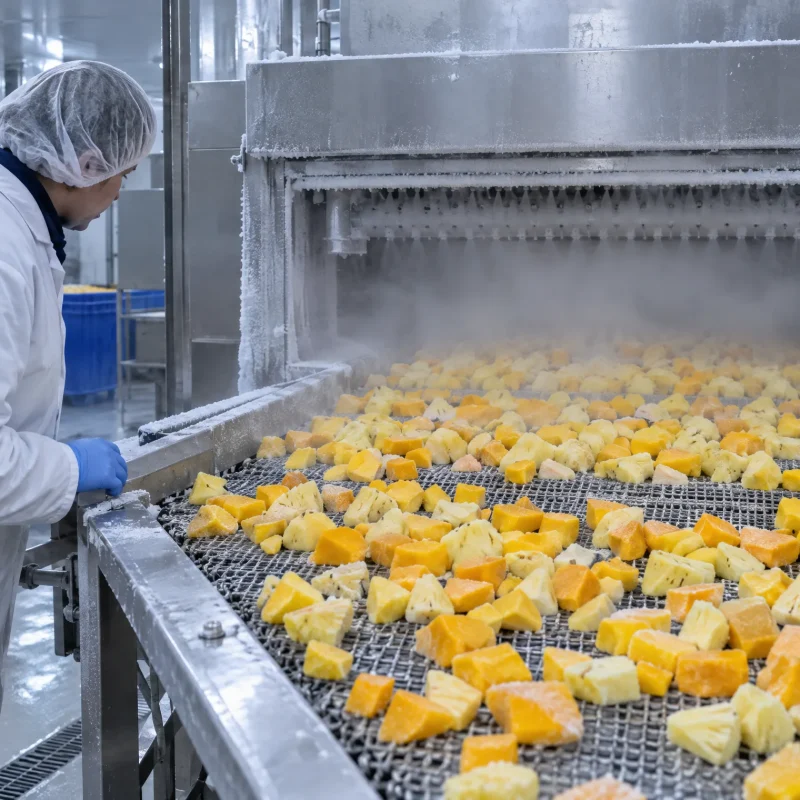
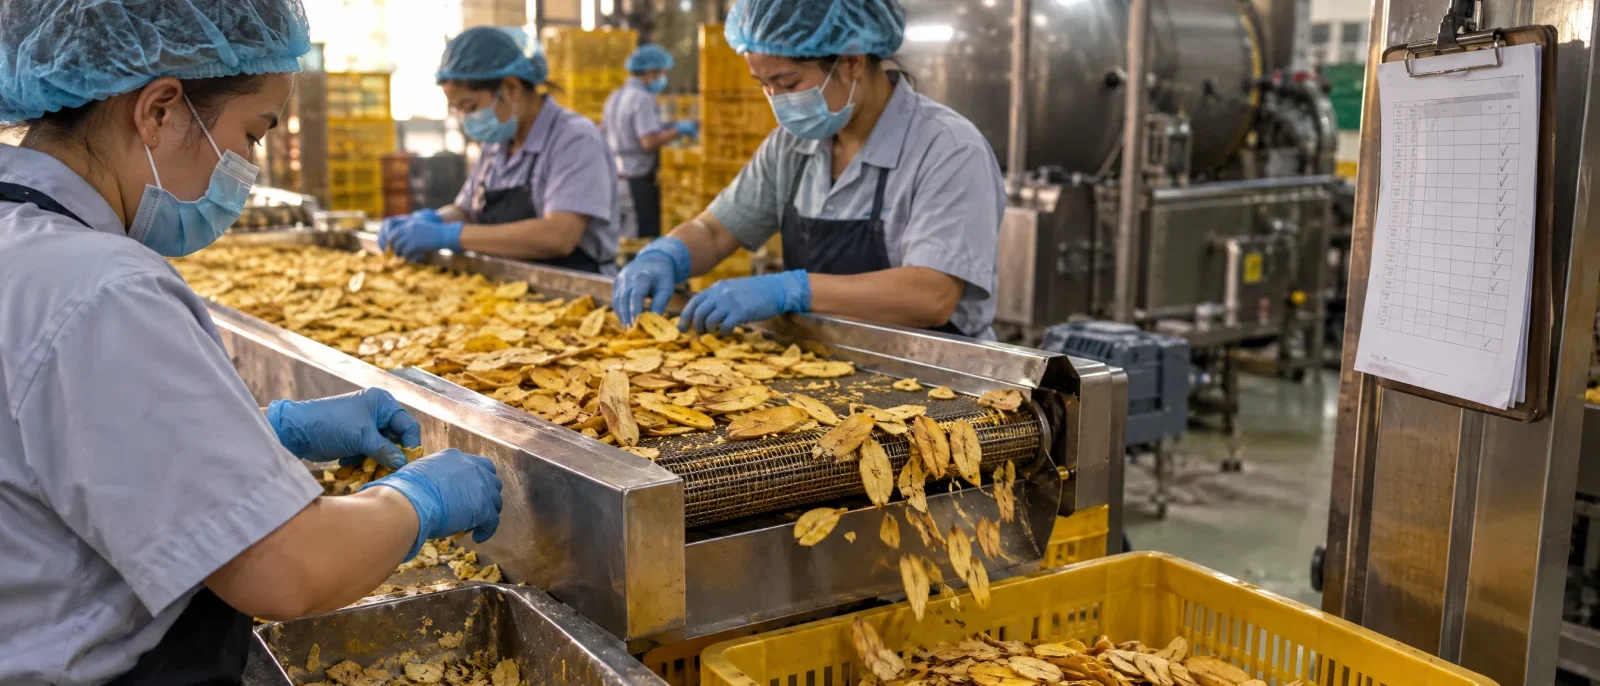
One is soft-dried: ripe fruit taken down slowly in a low-temperature dryer to a pliable chew, specified at 65 °Bx and above, nothing added. The other is vacuum-fried: 2 to 4 mm slices dropped into oil at roughly 90 to 100 °C under about 700 mmHg, then spun in a centrifuge to throw the surface oil off the slice before moisture-barrier packing. Both are ambient goods, and on a table a buyer cannot tell them apart. The tariff can, because the tariff reads the process. Both machines sit inside certified partner facilities, not on the exporter’s premises.
| Form | What the machine does | Added ingredients | Heading indicated | Source of that assignment |
|---|---|---|---|---|
| Fresh Cavendish, cartons | Ripening on an ethylene schedule | None | 0803.90 | The Vietnamese line 0803.90.20.00 recorded from shipment records |
| Soft-dried banana, nothing added | Low-temperature drying to 65 °Bx and above | None | 0803.90 (EU 0803 90 90) | Heading 0803 covers bananas fresh or dried; see below |
| Sugar-infused soft-dried banana | Soaked in sugar syrup, then dried | Sugar | 2008.99 | Sugar-infused then dried fruit goes to heading 20.08, as in UK ruling 600005639 on mango; confirm the eight-digit line in TARIC |
| Vacuum-fried banana chips | Frying under vacuum, then centrifuging | Vegetable oil, cane sugar | 2008.99 | Note 1(a) to Chapter 20; UK rulings 600008608 and 600007998 |
| IQF banana slice | Freezing | None | 0811.90 | Flagged as a correction to a published 0803.90 code |
What does Note 1(a) to Chapter 20 actually say?
It says that Chapter 20 does not cover fruit that has been prepared or preserved by a process belonging to Chapter 7, 8 or 11. That single sentence decides most of the question, and it decides it by process rather than by appearance or product name. Sugar enters through a second door. UK Advance Tariff Ruling 600005639 classified diced mango that was soaked in sugar syrup and then dried to heading 20.08, at 2008 99 48 99, and US ruling NY N230016 placed Thai dried mango of about 60% fruit and 40% sugar at 2008.99, while UK ruling 600012201 kept freeze-dried mango with nothing added in Chapter 8. A syrup soak before drying moves fruit out of Chapter 8; drying alone does not.
This Chapter does not cover: (a) Vegetables, fruit or nuts, prepared or preserved by the processes specified in Chapter 7, 8 or 11; […]
That is Note 1 to Chapter 20 as printed in the Customs Tariff Schedule of the Canada Border Services Agency, edition of 1 January 2024. Read it in reverse and it becomes an operating test. Drying is a process specified in Chapter 8, so dried fruit is pushed back out of Chapter 20 and stays in Chapter 8. Frying is not specified in Chapter 7, 8 or 11 at all, so fried fruit is never caught by the exclusion and lands in Chapter 20, heading 20.08. The same test, applied to a different fruit, is what separates dried jackfruit from jackfruit chips — though as the next section shows, the banana half of the framing does not transfer.
The World Customs Organization’s Explanatory Notes to heading 20.08 would add detail here. They are not published free of charge and have not been read for this article, so they are not cited. The chapter note carries the argument without them.
Which authority has already ruled on banana chips?
The United Kingdom, twice, on this exact product. Advance Tariff Ruling 600008608 covered banana slices of the Saba variety, dipped in a sugar solution and fried in coconut oil, with banana flavour, intended for food manufacturing. Advance Tariff Ruling 600007998 covered Cardava banana slices, dipped in sugar syrup and fried in coconut oil, packed in 8 kg cartons.
Both were classified to 2008 99 49 80. Both applied General Interpretative Rule 1, cited the Additional Notes to Chapter 20 and the Explanatory Notes, and treated the frying as the decisive fact. Two independent applications, one authority, the same conclusion. Both are publicly searchable at tax.service.gov.uk/search-for-advance-tariff-rulings, so a buyer can verify this paragraph in five minutes.
Two limits on how far those rulings reach. They named Saba and Cardava, which are cooking bananas. The varietal split on the Vietnamese side is documented: Cavendish goes to the fresh and frozen lines, and local ABB-group cooking varieties such as chuối sứ and chuối bơm go to the drying and frying lines. Higher dry matter is the trade’s explanation for that split rather than a measured recovery figure. No document links those Vietnamese lines to the varieties in the rulings, and the classification did not turn on variety in any case. Second, a US Customs and Border Protection ruling, R02151, is on record as touching this boundary. Its text could not be read, so nothing here describes what it held; if the United States is your import market, search CROSS for it and for your own goods.
Why is dried banana probably not heading 0813 at all?
Because banana is one of the few fruits that keeps its own heading in both states, and a national customs administration prints a duty rate that proves it. The standard 0813-or-2008 framing settles the jackfruit classification and most dried tropical fruit. It breaks on banana.
Heading 0803 covers bananas, including plantains, in both the fresh and the dried state: plantains at 0803.10 and other bananas, including Cavendish, at 0803.90. Heading 0813 is the residual heading for dried fruit, the place dried fruit goes when it has no heading of its own, and banana has one. The strongest evidence is not an argument but a rate: Japan Customs, in the tariff schedule effective 1 April 2024, publishes a separate duty line for dried banana under 0803.90 at a General rate of 6 percent, a temporary rate of 3 percent, and Free under both the WTO rate and the economic partnership agreement column. A customs administration does not print a dried-banana rate under a heading where dried banana does not belong. The commercial consequence lands inside that same subheading: fresh banana entering Japan pays a seasonal WTO rate of 20 to 25 percent, and dried banana pays nothing.
| Goods under heading 0803, Japan | Rate basis | Rate | Instrument |
|---|---|---|---|
| Fresh banana | General | 40% (1 Apr–30 Sep) / 50% (1 Oct–31 Mar) | Japan Customs, 01/04/2024 |
| Fresh banana | WTO | 20% / 25% | Japan Customs, 01/04/2024 |
| Fresh banana | CPTPP, Vietnam | 7.2% / 9.0% | Japan Customs, 01/04/2024 |
| Dried banana, 0803.90 | General / temporary | 6% / 3% | Japan Customs, 01/04/2024 |
| Dried banana, 0803.90 | WTO and EPA | Free | Japan Customs, 01/04/2024 |
The six-digit code that buyers and sellers exchange in emails does not tell you your duty. In Japan, the fresh-versus-dried split below the subheading is worth more than the CPTPP preference.
Why does the code on a supplier’s spec sheet disagree with the customs schedule?
Because a code on a specification sheet is an opinion, and the party printing it usually has no money at risk. Vietnamese export duty on banana is recorded as 0% with 0% export VAT and no export licence, sourced to customs-procedure practice rather than to the printed schedule. Whichever heading appears on the export declaration, the Vietnamese side pays the same. The entire consequence lands on the importer, and it lands at post-clearance audit rather than at the border.
Of four codes once published on this company’s own catalogue pages, two did not survive the evidence above: an IQF banana slice carrying 0803.90 that should have read 0811.90, and a soft-dried banana carrying 0813.40 against a national tariff schedule and two other research sources that point to 0803.90. An earlier version of this company’s own product sheet carried the code this article is questioning; the sheet now prints 0803.90 for plain soft-dried banana. The 0813.40 figure came from a web product page. That is not a resolution, because the printed nomenclature was not read at heading level for this article. It is a warning about which kind of source you are trusting, and the only thing that settles it for a given consignment is a binding ruling from the importing customs authority.
What does the wrong heading actually cost you?
Three things move when the heading moves, and all three are money: the duty rate, the origin rule, and the ingredient declaration on the pack. The third is the one that catches people, because it is the document that exposes a mismatch months after clearance.
Origin rules are written by chapter and heading. Under ACFTA the banana rule is regional value content of 40% or a change of tariff heading, so whether frying moved the goods from 08.03 to 20.08 is exactly the question a change-of-heading claim turns on. Get the heading wrong and a genuinely Vietnamese-origin preference can be voided on a technicality. Form E for China is still a paper certificate, and the industry assumption that it delivers 0% on banana is not verified here and should not be budgeted on.
VinFruits Global checks the dip-tank formulation at the partner facility against the ingredient declaration that will be printed on the carton before a consignment moves, because the printed ingredient line is what a post-clearance audit reads, not the specification sheet. Any anti-browning or sugar dip must appear in that declaration, and a dipped product cannot be labelled 100% banana.
On the EU side two published readings disagree, and neither is dropped here. Vietnam’s WTO Center at VCCI gives the EVFTA commitment as 100 EUR per tonne in 2020, falling to 90 in 2022, 80 in 2024 and 75 EUR per tonne from 2025, cited against HS 08039010, the fresh line, which is 1,275 to 1,500 EUR on a 17 to 20 tonne container. A second source reads the EU position as 0% inside an ACP quota with 176 EUR per tonne outside it. The rate for dried banana, EU line 0803 90 90, was not retrieved: the famous EU banana duty is a fresh-banana duty, and a buyer who applies it to a dried consignment has budgeted the wrong number. For the United States, HTS 0811.90.80 frozen fruit carries MFN 14.50% with Vietnam not on the duty-free list; that is a frozen rate, and the 2008.99 rate was not retrieved.
Why can’t you find reliable trade data for dried banana?
Because the heading that cannot distinguish the two products also cannot count them. Residual “other” lines such as 1404.90, 0810.90 and 1106.30 carry hundreds of unrelated goods, so any trade value pulled by code alone is not a banana number. Only shipment records that carry a goods description are usable.
Volza’s shipment records put Vietnam third in the world for dried banana with 4,747 shipments, 764 buyers and 428 suppliers, behind Ecuador at 11,945 and Uganda at 5,606, with the global line up 107% over twelve months and Korea, the United States, Russia and Hong Kong as the observed destinations. Tridge’s February 2026 figures under HS 2008.99 for dried banana run from 2.50 USD/kg for the Philippines to 13.42 for Germany, with Vietnam at 4.78; that spread is evidence of a mixed basket, not a price signal. Treat both as published third-party observations with a short shelf life.
What should you ask before you accept a code on an offer?
Five questions, in this order, before the code goes anywhere near a landed-cost sheet. All of them are answerable by the plant that made the goods.
- Is there any added oil, fat or sugar in this product? Oil from frying, or sugar from a syrup soak before drying, is what separates Chapter 20 from Chapter 8.
- Send the ingredient declaration exactly as it will be printed on the carton, not the marketing description.
- Which machine produced it: a low-temperature dryer or a vacuum fryer? Ask for the process temperature and, for fried product, the vacuum condition.
- Was the fruit dipped before drying or frying, in sugar syrup or in an anti-browning solution, and is that dip on the declaration?
- Which eight-digit line will appear on the Vietnamese export declaration, and does it match the code on the specification sheet?
Two clauses worth pasting into the purchase order. First: the ingredient declaration printed on the carton shall match the formulation used in production, and any change to the dip or the frying medium is a specification change requiring written approval before shipment. Second: classification is determined by a binding ruling obtained from the customs authority of the destination market before the first shipment, and the code shown on the supplier’s specification is indicative only. On documents, banana is recorded among the fruits exempt from EU phytosanitary certification; verify the current annex to Regulation (EU) 2019/2072 before your first consignment rather than assuming it.
What is still open, and what would settle it?
Five things are genuinely unresolved, and naming them is more useful than filling the gaps with plausible numbers. Each has a document that would close it.
| Open question | Why it is open | What settles it |
|---|---|---|
| Whether plain soft-dried banana is 0803.90 or 0813.40 at your border | Heading 0803, Japan’s schedule and the EU line 0803 90 90 point to 0803; an earlier version of this company’s own sheet printed 0813.40 | A Binding Tariff Information in the EU or UK, or an Advance Ruling in the US, on the actual goods |
| Vietnam’s eight-digit lines for the dried and fried forms | Only the fresh line 0803.90.20.00 is documented from shipment records | The printed Vietnam import-export tariff schedule, or a licensed customs agent |
| The EU duty on dried banana of Vietnamese origin | Only the fresh line 08039010 was retrieved | TARIC consultation at eight or ten digits for the dried line |
| The US rate for 2008.99 banana chips, and 2026 reciprocal exposure for Vietnam | Not retrieved | USITC HTS and CBP |
| What CBP ruling R02151 held | The ruling text was not accessible | CROSS |
Korea is a separate warning. The base rate is 30%, and Korea Customs operated a 0% tariff-rate quota of 200,000 tonnes for the first six months of 2025, with the 2026 position not retrievable. The Philippines–Korea free trade agreement entered into force on 31 December 2024 and is eroding Vietnam’s margin on a five-year schedule. Do not assume the quota persists.
Common questions
Is the HS code for banana chips 0813 or 2008?
Neither code covers both products. Vacuum-fried banana chips are fried, and frying is not one of the processes specified in Chapter 7, 8 or 11, so they fall in Chapter 20. The United Kingdom classified fried banana slices to 2008 99 49 80 in Advance Tariff Rulings 600008608 and 600007998. Soft-dried banana with nothing added stays in Chapter 8, and heading 0803 covers bananas fresh or dried. Banana soaked in sugar syrup before drying moves to heading 20.08.
Why does frying change the chapter when drying does not?
Note 1(a) to Chapter 20 excludes fruit prepared or preserved by the processes specified in Chapter 7, 8 or 11. Drying is one of those processes, so dried fruit is pushed back into Chapter 8. Frying is not listed, so fried fruit falls outside the exclusion and into heading 2008. Sugar matters too: fruit soaked in sugar syrup before drying is prepared fruit of heading 20.08, as UK ruling 600005639 decided for mango, while plain drying stays in Chapter 8.
What is the HS code for soft-dried banana, and why do suppliers disagree?
With nothing added, 0803.90. Heading 0803 covers bananas including plantains, fresh or dried, Japan Customs publishes a separate duty rate for dried banana under 0803.90, and the EU line is 0803 90 90. An earlier version of this company’s own sheet printed 0813.40. If the banana was soaked in sugar syrup before drying, it moves to heading 20.08. A binding ruling from your customs authority settles it for your goods.
Does the heading affect my EVFTA or CPTPP preference claim, or only the duty rate?
Both. Origin rules are written by chapter and heading, so the heading you declare decides which rule you must satisfy. The EVFTA and CPTPP product-specific rules for 08.03 and 20.08 must be read in each agreement’s annex at your exact code. Under ACFTA, for comparison, the banana rule is regional value content of 40% or a change of tariff heading, and whether frying moved the goods from 08.03 to 20.08 is exactly what a change of heading turns on. A wrong heading can void a genuinely Vietnamese-origin claim.
Why can’t I find reliable trade data for dried banana?
Because code-level trade data cannot tell a dried slice from a fried chip, and the 2008.99 basket mixes many unrelated prepared fruits, so any value pulled by code alone is not a banana number. Only shipment records carrying a goods description are usable. Volza recorded 4,747 dried-banana shipments from Vietnam, 764 buyers and 428 suppliers, ranking Vietnam third behind Ecuador and Uganda.